All Categories
Featured
Individual Medical Insurance Options for Seniors
Leaving military service means leaving behind Servicemembers 'Group Life Insurance (SGLI)and figuring out what comes next can be confusing.(Veterans' Group Life Insurance coverage )group term protection offered when you have actually separated from service, covered in detail below.(Veterans Affairs Life Insurance)guaranteed-acceptance whole life insurance coverage for veterans with a service-connected impairment, likewise covered listed below.
Independent Insurance AgencyVGLI(Veterans 'Group Life Insurance Coverage )is group term life insurance coverage readily available to eligible veterans and former service members after they leave the military. Your preliminary protection quantity is normally based on the SGLI coverage you had while serving, and you can apply to increase it over time up to the$ 500,000 maximum. VGLI premiums are based on your age and how much protection you choose they generally increase as you get older.
Independent Insurance Agency
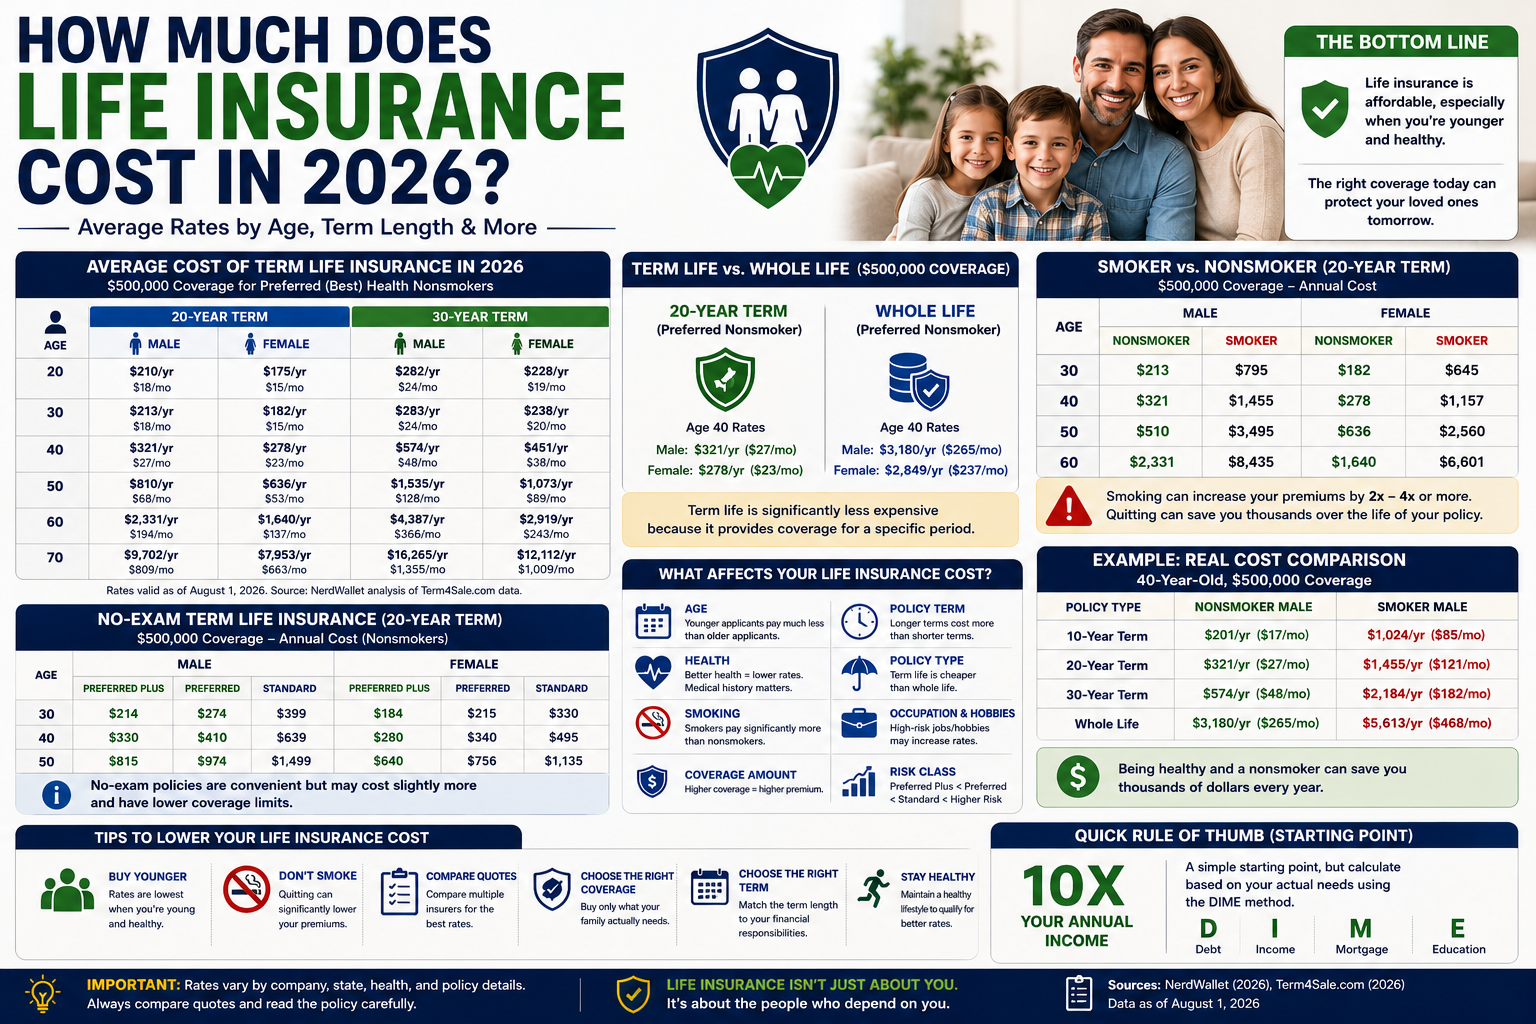
Because eligibility has particular conditions, validate your precise eligibility on rather than presuming based upon age alone. VALife is entire life insurance, suggesting it's permanent coverage( not term )that can develop cash worth gradually, and premiums are repaired based upon your age when you enroll they do not increase later on because of age or health modifications. S-DVI stopped accepting brand-new applicationsafter December 31, 2022, and VALife is its replacement program. Here's how the two programs compare, side by side. Neither is widely better they're built for various scenarios. Veterans/former service members who had SGLI, applying within the eligibility window after separationVeterans age 80 or younger with a qualifying service-connected special needsrating (certain veterans 81+might likewise qualify)$10,000 to$500,000 Up to $40,000, in $10,000 incrementsNoneFull face worth usually starts after 2 years of paid premiums; earlier death normally returns premiums paid plus interest VA is specific that veterans can use for private life insurance at any time, separate from VGLI or VALife. See VA's guidance onprivate insurance. Private insurance isn't immediately much better or worse than VA coverage it's a different set of tradeoffs. Private policies typically include medical underwriting( health questions, often a test), and pricing and eligibility differ by insurer. Some veterans discover personal coverage expenses less than they anticipate if they remain in health; others find VA's guaranteed-acceptance or no-health-review options better specifically because those questions do not use to them. Yes. VA is specific on this point: you can apply for both VGLI and a private life insurance policy they're not mutually special. This can make sense if you desire more total coverage than VGLI alone offers, or if you just want to compare youroptions side by side before devoting. If you're doing this, timing matters. See the "Veterans With Health Conditions"section listed below it's particularly about securing your VGLI eligibility while you're likewise checking out personal protection. For a deeper side-by-side look at how VGLI and private coverage compare consisting of when each may make more sense see our full comparison: VGLI vs. There's no single formula that fits everyone, and basic guidelines(like"10 times your earnings" )can be an affordable starting point however frequently miss what reallymatters for your scenario. Some of the elements worth analyzing: just how much of your income would your household require replaced, and for the length of time? balances that would still need to be paid if you weren't there to pay them. if you're wishing to assist money a child's education. funeral, burial, and associatedexpenses. SGLI, VGLI, VALife, company coverage, or cost savings you already have that would offset what's required somewhere else. what your household might reasonably make use of, consisting of any survivor benefits. Weighing all of this by hand is a lot. For a closer take a look at these factors and how they mesh, see How Much Life Insurance Do I Need?. If your primary issue is last expenses specifically funeral and burial expenses rather than income replacement LifeCoverPath's is constructed around that instead. If you have a health condition, timing your VGLI application matters more than almost anything else in this guide. For more on weighing VGLI against personal coverage without risking your VGLI timing, see VGLI vs. Private Life Insurance: What Veterans Ought To Know.

Latest Posts
How Whole Insurance Protects Future Wealth
Why Whole Life Insurance Protects Families
Final Expense Coverage Options for Veterans